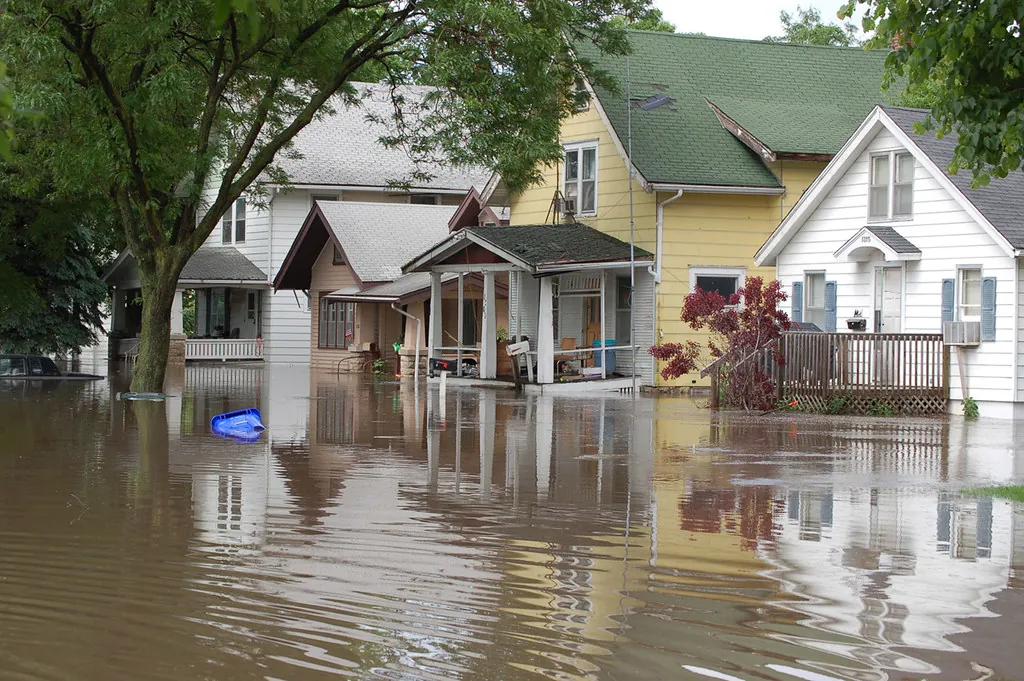
Hurricane claim appraisal in Rhode Island carries the weight of history. The 1938 New England Hurricane and Hurricane Carol in 1954 pushed storm surge into downtown Providence, which led to the Fox Point Hurricane Barrier. Hurricane Bob in 1991 battered the coast, Tropical Storm Irene in 2011 and Superstorm Sandy in 2012 damaged homes and dunes from Westerly to Narragansett, and Henri made landfall near Westerly in 2021.
Hurricane deductibles
Many Rhode Island homeowner policies carry a hurricane or named-storm deductible expressed as a percentage of dwelling coverage, commonly between 1% and 5%. On a house insured for $500,000, a 2% deductible is $10,000. The policy defines what triggers it, so the first step in any hurricane claim is confirming which deductible applies and calculating it correctly.
Wind versus flood
Standard homeowner policies exclude flood, including storm surge. Flood damage is covered, if at all, under a separate flood policy such as one through the National Flood Insurance Program. In a coastal storm, the same house can have wind damage to the roof and flood damage to the first floor. Appraisal under the homeowner policy values the wind-related loss; it doesn’t decide coverage for flood. We separate the two carefully so each policy is presented with the right scope.
Our wind vs. flood damage splitter helps you organize a mixed loss before you talk to either carrier.
Inland hurricane damage
Hurricanes don’t stop at the beach. Wind damage and falling trees reach Cranston, Coventry, Smithfield and the rest of the state. Inland claims are valued with the same care, often with fewer complications about flood.
Questions about hurricane & tropical storm claims
What is a hurricane deductible?
It’s a separate deductible, usually a percentage of your dwelling coverage, that applies when the storm meets the conditions your policy describes. It’s often much larger than your standard deductible.
Does appraisal cover storm surge damage?
Appraisal under a homeowner policy values the covered loss. Storm surge is usually excluded from homeowner policies and covered, if at all, by a separate flood policy.
My home is inland. Do hurricane rules still apply?
If your policy’s hurricane deductible is triggered, it can apply statewide, not just on the coast. Check the trigger wording in your policy.