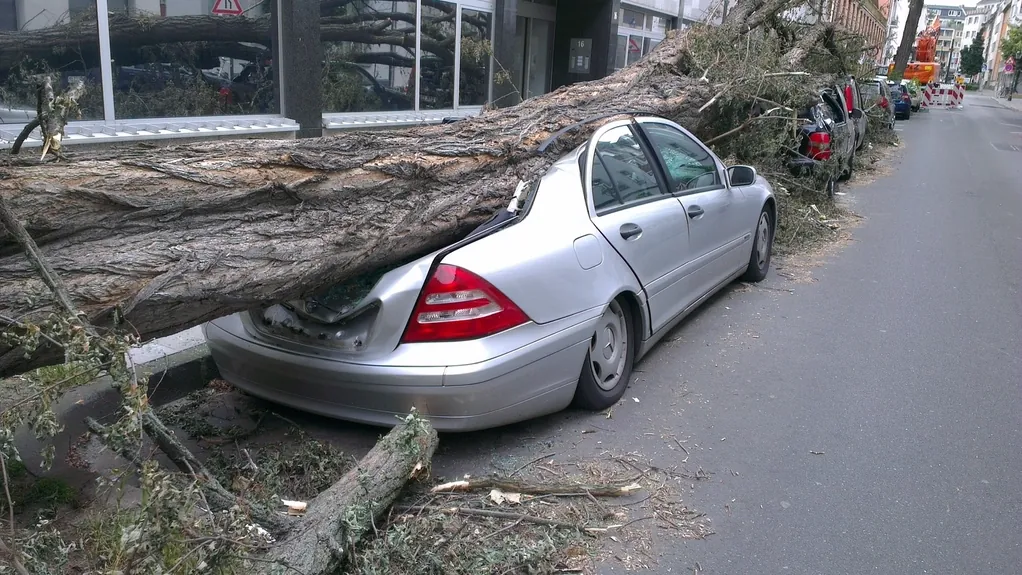
Wind damage insurance appraisal in Rhode Island usually traces back to a nor’easter. These coastal storms can blow for a day or more, peeling shingles and siding, driving rain into walls and toppling trees onto houses. The October 2017 storm knocked out power to a large share of the state, and many winter nor’easters bring gusts strong enough to damage roofs well inland. Summer thunderstorms add downbursts, and tornadoes do occasionally touch down here, though they are rare.
What a complete wind scope includes
- Every damaged slope and elevation, not just the one facing the storm
- Siding, trim, gutters and windows, including matching on the undamaged sides where the policy supports it
- Interior water damage from wind-driven rain
- Tree removal from the structure and the repairs underneath it
- Fencing, sheds and other structures under their own coverage
Which deductible applies?
Some Rhode Island policies apply a separate hurricane or named-storm deductible, often a percentage of dwelling coverage, when specific weather conditions are met. A nor’easter normally falls under the standard deductible, but the trigger language in your policy decides. Our hurricane deductible calculator shows how the two compare.
Documenting wind damage
Take wide photos of every side of the house as well as close-ups. Note the date and the storm. Keep damaged pieces of siding or shingles when you can; they help show product type and age.
Questions about wind, microburst & tornado damage
Does a nor’easter trigger my hurricane deductible?
Usually not, because hurricane deductibles are typically tied to a named storm or hurricane conditions. But the trigger wording varies, so read your policy or ask us to look at it.
Are tornadoes covered differently?
Tornado damage is generally treated as windstorm damage. The question in appraisal is the cost of the repairs, not the type of wind.
A tree fell on my house. Is removal included?
Many policies pay to remove a tree that damaged a covered structure, sometimes subject to a limit. The repair underneath is valued as part of the dwelling loss.