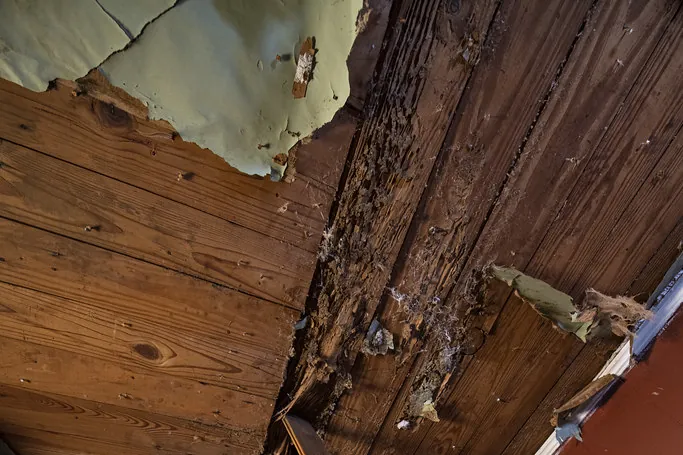
Water damage claim appraisal in Rhode Island covers the most common type of interior loss we see. Older plumbing in pre-war homes, washing machine and water heater failures, ice-dam leaks and rain driven through walls during coastal storms all show up regularly. The damage is often bigger than it looks on the day it happens.
What a water scope should include
- Moisture mapping to find where water traveled behind finishes
- Emergency services and drying, with equipment counts and days that match the job
- Removal and replacement of saturated drywall, plaster, insulation and flooring
- Cabinetry and trim that can’t be removed without damage
- Painting to a logical break, not just the stained patch
- Damage to units below in multi-family buildings
Coverage limits to watch
Policies treat sudden leaks, long-term seepage, surface water and sewer backup differently, and many cap mold remediation. Backup of sewers and drains usually needs a separate endorsement. These are coverage questions; we flag them and value the covered portion.
After a freeze
Burst pipes during a cold snap often combine with ice-dam leaks. Our ice dam and frozen pipe service covers those winter losses in detail.
Questions about water damage & leak claims
The carrier only paid for the stained area. Is that normal?
It’s common in first estimates. Water usually spreads further than visible staining, and paint and finishes need to be matched to a logical break.
Is sewer backup covered?
Often only if you bought a water backup endorsement. That’s a coverage question; if it’s covered, appraisal can resolve the cost.
Do you value mold remediation?
Yes, where it’s part of the covered loss. Many policies cap mold, so we separate it clearly in the estimate.